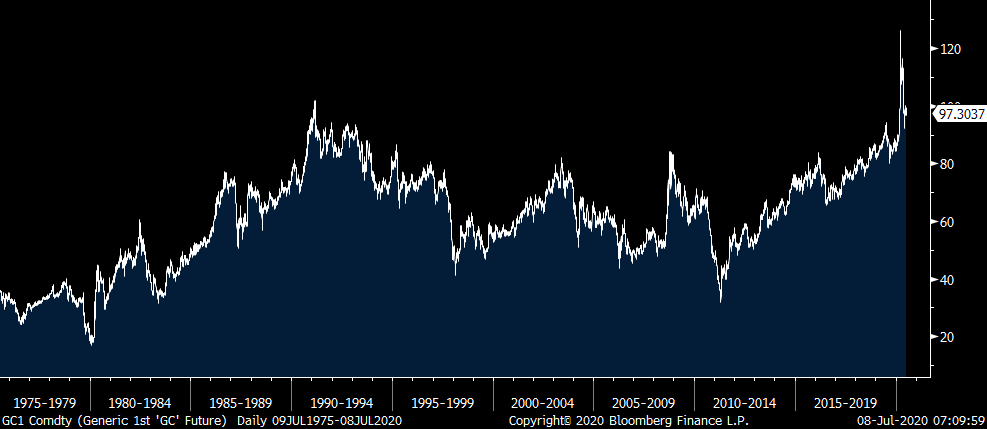
Rich Clarida late yesterday did his best Harohiko Kuroda imitation, the Governor of the Bank of Japan. Clarida said “We have a lot of accommodation in place; there’s more that we can do, there’s more that we will do, if we need to.” Just keep on suppressing interest rates, encourage more debt accumulation and further distort markets when all we need is a vaccine and/or effective therapeutics which Clarida essentially acknowledged. Considering where the cost of capital is for the US Treasury and and investment grade companies, I’m not clear on what more they can do unless they get into the lower quality part of the credit spectrum which is a whole other slippery slope. Hearing this from the Vice Chair and it should be no surprise that gold continues to move higher and which I remain bullish on. For perspective, if you inflation adjust (via CPI) the 1980 high of $850, gold would be around $2600 today just to get back to the same level.
GOLD going back 40 yrs

Here is the ratio of gold to silver, just under 100 and which compares to the 45 year average of 61. Silver thus has some catching up to do.
There was no change in the Hong Kong dollar at the upper end of the 7.75-7.85 peg range to the US dollar in response to the chatter about the US administration wanting to disrupt the peg. I’m not clear on how that would actually happen but it seems inevitable that the peg breaks at some point anyway in coming years and it gets pegged to the yuan instead. The Hong Kong dollar has traded well in part because of higher rates relative to the US with HIBOR above LIBOR.
After a one week respite, bullish sentiment has gotten extreme again with the Bull/Bear spread just below 40 at 39.4 vs 34.7 last week. Bulls rose to 57.7 from 54.5 and that is the highest since January 22nd. Bears fell for the 14th week in the past 15, down to just 18.3 and the lowest since that date in January. II said “Our rules says bulls above 55% calls for defensive measures, tight stops at the minimum and possibly some selling among shares with big gains.” This bullishness on the part of ‘professional’ investors is in contrast to the mood of individuals, which is more suspect, who I believe are voting on the economy while the II is capturing just a stock market price chase. We’ll see the AAII number tomorrow.
After a two week lull, purchase applications picked up by 5.3% w/o/w and which brings the y/o/y gain to 33% which is quite impressive considering the state of the economy. We assume that the move to the burbs from cities continues with the help of low rates. The question again is after this pent up demand is satiated, will the industry settle in and be driven by the plain vanilla things like employment, wages and demographics. Refi’s were little changed but remain up by 111% y/o/y.
 Peter is the Chief Investment Officer at Bleakley Advisory Group and is a CNBC contributor. Each day The Boock Report provides summaries and commentary on the macro data and news that matter, with analysis of what it all means and how it fits together.